All Categories
Featured
Finding Vital 2026 Hardship Help for Stressed Households
Expert Analysis Into New Credit Consolidation Strategies


Tips to Reduce Credit Card Debt in 2026
Table of Contents
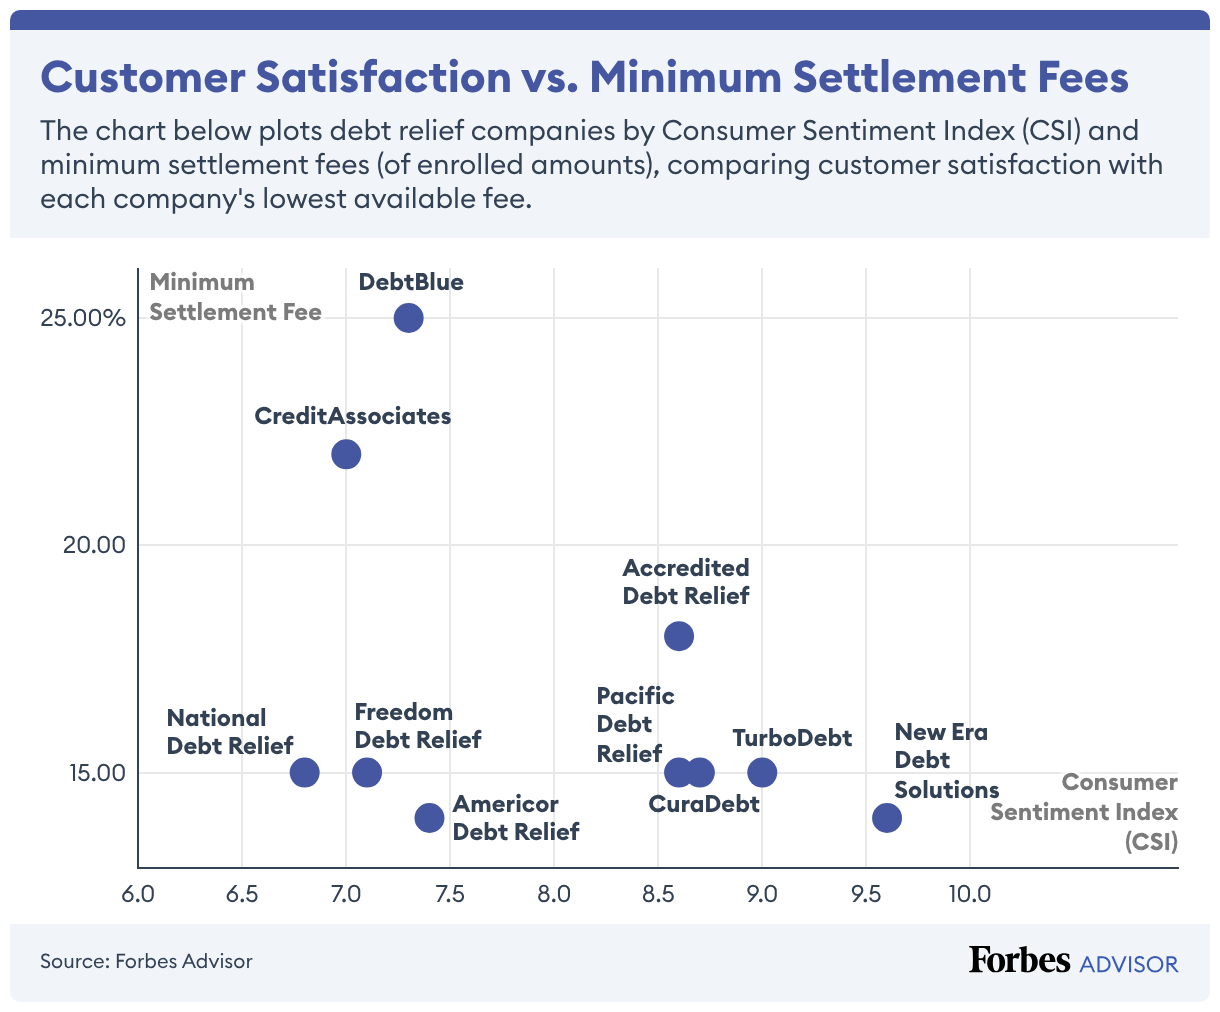
Some loans require collateral, such as your home or car. You can try to make these settlements yourself, or work with a financial obligation settlement company that negotiates on your behalf.
This can be an exceptionally risky solution for dealing with debt, so it is very important to comprehend the advantages and disadvantages: You'll acquire costs from your creditors and from the financial obligation settlement agency, but there's a possibility of saving cash when it's all over with. While some lenders will not negotiate a settlement, others might accept a lump amount for as little as 50% of what you owe.
That may look like permanently, however for some debtors this could indicate being debt free earlier than if they paid off their full financial obligation balances on their own. Several consumer advocacy firms caution people against utilizing debt settlement, consisting of the Federal Trade Commission (FTC) and the Customer Financial Protection Bureau (CFPB).
It can take as much as three years or more to conserve up enough money for settlement offers, a lot of customers end up leaving of their financial obligation settlement program before they have actually settled their financial obligations. Debt settlement can damage your credit report just as much as submitting personal bankruptcy, and settled financial obligations will remain on your credit reports for 7 to 10 years.
Mastering Debt Management Strategies in 2026
Debt settlement business declare they can get as much as 70% of your charge card financial obligation forgiven, but the reality is that your lenders may decline to work with a financial obligation settlement business. The internal revenue service requires you to report forgiven financial obligation of $600 or more as taxable earnings, so you might need to pay more taxes after debt settlement.
In addition to debt settlement, there might be other methods to have some of your debt forgiven., or other special options from lending institutions who forgive debt due to financial challenges.
Here are some of the pros and cons of going this route: If you qualify for a genuine loan forgiveness program, you could gain from having actually financial obligation forgiven. You'll likely still have to pay a few of it back, however the cost savings might be a huge financial assistance. Debt forgiveness rip-offs have actually ended up being increasingly common because the pandemic, particularly student loan scams.
Deep Analysis of Household Debt Services
There's no assurance that you'll qualify to file, however declaring Chapter 7 insolvency could result in having your financial obligations canceled, and a Chapter 13 insolvency might get you into a 3-5 year payment plan to eliminate debt. Here's what you should consider:. Some debtors have no feasible way to pay back all of their debt.
When you submit for insolvency, the court issues an automatic stay, implying that creditors will be disallowed from making collection attempts on your financial obligations through telephone call and letters. Once you submit, financial institutions will deal solely with your lawyer and not you. When you declare insolvency your lenders need to stop all foreclosure and foreclosure procedures.
Personal bankruptcy is among the most damaging events for your credit, and it remains on your credit reports for 7-10 years after you submit. This might suggest being rejected brand-new loans and credit in the near future. You'll have to pay for a lawyer, plus court filing charges, paralegal fees, personal bankruptcy trustee fees and fees for the necessary customer therapy.
You don't need to work with a third-party to get debt-relief. In truth, some alternatives for reducing debt might conserve you cash and help maintain your credit The finest option for you may even include a combination of DIY options, budget plan tools or funding options. Here are some of the things you can do by yourself: Are you clear on where all your cash is going? If you don't keep track, there are most likely a lots of costs you do not understand are setting you back.
Expert Debt Consolidation Reviews for 2026
Here's what you ought to consider:. Some debtors have no practical way to pay back all of their debt.
, meaning that financial institutions will be barred from making collection attempts on your financial obligations through phone calls and letters. When you submit for insolvency your creditors must stop all foreclosure and repossession proceedings.
Personal bankruptcy is one of the most damaging occasions for your credit, and it stays on your credit reports for 7-10 years after you submit. This could imply being denied new loans and credit in the near future. You'll have to spend for a lawyer, plus court filing charges, paralegal charges, insolvency trustee costs and costs for the necessary customer counseling.

You don't need to deal with a third-party to get debt-relief. In truth, some choices for reducing financial obligation could save you money and help protect your credit The finest service for you might even include a mix of do it yourself solutions, budget plan tools or funding alternatives. Here are some of the things you can do on your own: Are you clear on where all your money is going? If you do not keep track, there are probably a lots of costs you do not realize are setting you back.

Latest Posts

Finding Vital 2026 Hardship Help for Stressed Households
Managing Excessive Consumer Debt in 2026
Expert Analysis Into New Credit Consolidation Strategies