All Categories
Featured
Finding Vital 2026 Hardship Help for Stressed Households
Expert Analysis Into New Credit Consolidation Strategies


How to Eliminate Credit Card Debt in 2026
Table of Contents
Throughout this time, the Department of Education could renew your commitment to your loans if it's figured out that you're no longer handicapped, your family earnings exceeds particular permitted limitations, or you take out new federal trainee loans. The Civil Service Loan Forgiveness (PSLF) Program offers forgiveness for particular federal borrowers who work for qualified employers.
To get approved for federal student loan forgiveness, you need to: Make 120 certifying payments toward your loansBe employed by a U.S. federal, state, local, or tribal federal government, or a nonprofit company Work full-time for that firm or organizationOwe eligible Direct Loans (or combine other federal loans into a Direct Loan) Register in an income-driven repayment planIf you skip payments throughout your loan grace duration, while you're registered in school, or throughout specific deferment and forbearance durations, those won't count towards the 120 qualifying payments you require for loan forgiveness.
To get this benefit, you'll need to submit a PSLF form accrediting that you were employed with an eligible company or agency for the period of the forbearance duration. If you worked complete time for AmeriCorps or as a Peace Corps volunteer, you can count that time toward your certifying service requirement.
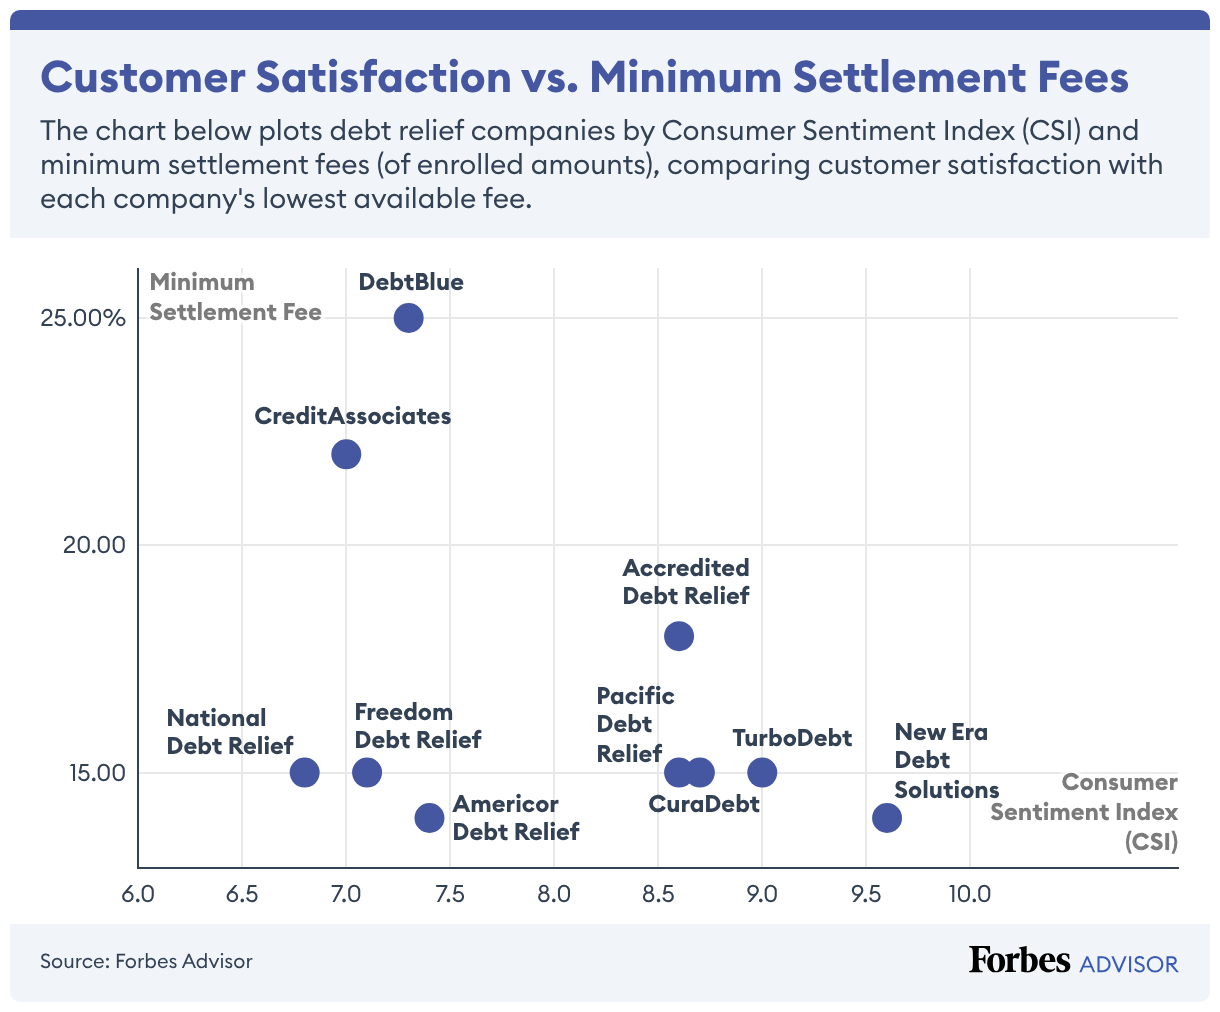
There is no government financial obligation relief program for credit cards. Financial obligation relief companies use services to assist you manage and pay off credit card debt for less than you owe. When you settle credit card debt, you and the credit card business agree on a quantity you'll pay, which is less than the overall balance you owe.
If you do not have a swelling amount to use your creditors (many people don't), you may choose to stop making credit card payments and rather reserved cash in a devoted account. If you stop paying your financial institutions for any reason, anticipate credit history damage and collection efforts. When you have enough conserved to use your creditors, settlements can start.
Tackling Rising Household Debt in 2026
Bankruptcy filings are public records and can make it difficult to get tasks in specific fields. You likewise provide up control when you file bankruptcythe court tells you how much you will pay (Chapter 13) or what possessions you need to quit (Chapter 7) to please your lenders. Personal bankruptcy has a major unfavorable impact on your credit history.
On the professional side, debt settlement might help you get out of debt quicker than making minimum payments, considering that you're paying less than the overall balance. A disadvantage of choosing debt settlement for financial obligation relief is that it's most likely to harm your credit standing. Keep in mind, however, that if you're currently falling behind on your payments, the chances are good you've currently seen an unfavorable impact on your credit report.
If you're thinking about charge card financial obligation relief programs, research your choices carefully. Examine the services used, the costs, and online evaluations to see what other individuals are stating. Despite which debt relief program you choose, the most crucial thing is taking action to get your finances and credit back on track.
Customers with federal government student loans might certify for income-driven payment plans. These strategies can make a big difference. This assists make sure you can pay for those payments.
How to Erase Credit Card Debt in 2026
Working long enough in certain public service occupations might certify you to have the rest of your financial obligation forgiven. So could paying into an income-driven repayment program for 20 or 25 years. If you've become completely and completely disabled, you may not have to repay your student loans. Inspect for more information and to learn if you qualify.
Tackling Excessive Consumer Debt in 2026Trainee loan impairment discharge needs evidence of your condition. These programs are for people in real requirement, so not everyone will qualify. In many cases, forgiven debt is gross income. Nevertheless, debt forgiven under federal student loan programs is normally an exception. There are a couple of states where forgiven federal trainee loan financial obligation may be dealt with as taxable income.
Let's address some typical misconceptions about federal government debt relief programs to clear up any confusion. Truth: In lots of cases, Internal revenue service and student loan debt forgiveness programs are based on your ability to pay.

Federal government financial obligation relief programs don't cover all types of debt, but there are other choices that can assist. Here's what you can do if you have debt problems the federal government can't resolve.
2026 Guide to Successful Debt Resolution
These organizations consist of personal financial obligation relief business and not-for-profit credit counselors. Here are a few of the solutions they may use: Hardship programs: Numerous creditors provide hardship programs to help you get through tough times. These programs may minimize or stop briefly payments, lower rates of interest, or waive costs for individuals experiencing monetary trouble.
This could result in substantial financial obligation decrease. Credit therapy: A licensed credit therapist can help you develop a budget and find out money management skills if you register in their financial obligation management program.
Countless Americans are battling with credit card debt, and in 2026, some might certify for relief through credit card financial obligation forgiveness programs. These initiatives, offered by major credit card issuers and monetary institutions, are developed to help qualified consumers reduce or remove impressive balances under particular conditions. Eligibility for charge card financial obligation forgiveness usually depends on numerous crucial aspects:: Individuals experiencing substantial monetary obstacles, such as job loss, medical emergencies, or unexpected household costs, may qualify.
Lenders might provide a settlement where a portion of the debt is forgiven in exchange for a lump-sum payment or a structured payment plan.: Some programs need proactive engagement with the credit card company. Customers might deal with a financial therapist or directly with the financial institution to work out a settlement quantity that is lower than the overall balance owed.
Evaluating Best 2026 Credit Relief Options
This typically needs cautious budgeting to guarantee the settlement can be satisfied completely.-: Structured payment programs collaborated by credit therapy firms may consist of forgiveness stipulations if the customer successfully finishes the intend on time.-: Some companies use momentary decreases in interest rates, waived charges, or partial financial obligation forgiveness to account holders experiencing financial hardship.

Latest Posts
Finding Vital 2026 Hardship Help for Stressed Households
Managing Excessive Consumer Debt in 2026
Expert Analysis Into New Credit Consolidation Strategies